
Back in May, we posted a short video with a look ahead: rising insurance costs could become one of the biggest forces in the California housing market this fall. At the time, the California FAIR Plan had just announced a 29.1% average rate increase, set to start October 15.
That date has now passed, and the increase is in effect. Then, the day after it took effect, a wind-driven fire tore through neighborhoods in San Clemente and San Juan Capistrano. The two events landed in the same week, and together they show exactly why insurance has moved to the center of every buying and selling decision in Southern California.
Fire season is a reminder
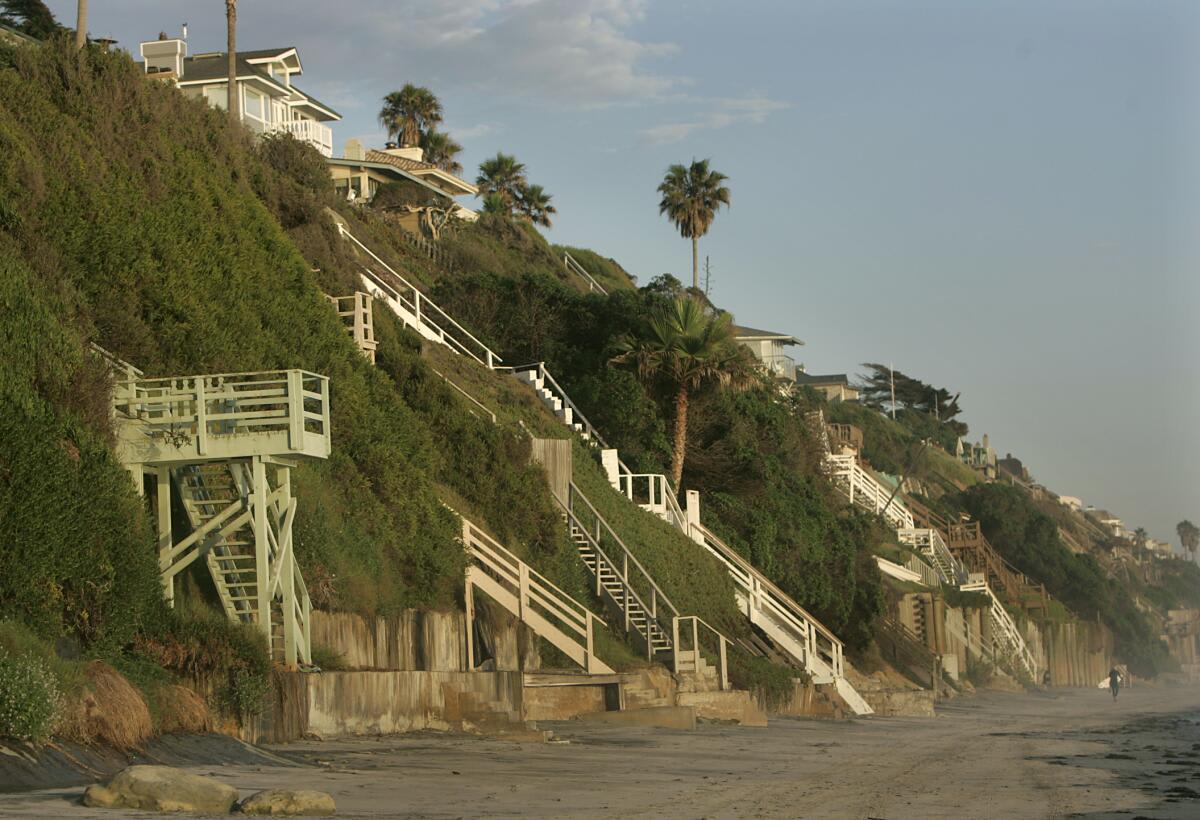
In mid-October, the season's first Santa Ana winds brought the Norte Fire to San Clemente and San Juan Capistrano, along with fires near Camp Pendleton and in Malibu. The Norte Fire burned 570 acres, destroyed or damaged at least seven homes, and briefly put about 16,000 residents under evacuation orders.
Events like these are why insurers price risk neighborhood by neighborhood. A home's location now shapes its carrying costs. Here's where rates stand, and what buyers and sellers can do about it.
Where insurance rates stand now
As of October 15, FAIR Plan rates are up an average of 29.1% for new and renewal dwelling policies. The California Department of Insurance approved the increase after the FAIR Plan asked for 35.8%.
The word "average" matters. Homes in high wildfire-risk areas can see larger increases, and some lower-risk policyholders may see decreases. Under the original request, about four in five policyholders would have faced increases between 5% and 60%.
Why this matters so much: the FAIR Plan is California's insurer of last resort, and more homeowners rely on it every year. It held about 464,900 homeowner policies in fall 2024 and nearly 700,000 by June 2026, as private insurers pulled back from fire-prone areas.
For individual homeowners, the jumps can be steep. One Vista homeowner told ABC 10News her FAIR Plan premium rose from about $900 to $4,000 a year after her fire-zone rating changed. For a home with about $2 million in dwelling value, one broker estimates FAIR Plan coverage at $10,000 to $12,000 a year or more.
What this means for buyers
Insurance is now part of what you can afford, not an afterthought at closing. An extra $1,200 a year in premiums adds about $100 to your monthly payment, and in high-risk areas the increase can be much larger.
Get an insurance quote before you write an offer. Ask for quotes early, especially in canyon, hillside or wildland-edge neighborhoods. Your lender will require coverage before closing, and this is part of your contingency period as a buyer..
Budget the full monthly cost. Add the premium to your mortgage, taxes and HOA dues when you set your budget.
Ask about the home's history. On seller disclosures, look for the answer to the question about past insurance claims, the roof's age and fire-hardening upgrades can all affect what an insurer charges or whether it will write a policy.
Use the moment. If higher carrying costs thin out the buyer pool, as we expected back in May, buyers who come in prepared may find more room to negotiate.
What this means for sellers
Buyers are now pricing insurance into their offers. A $6,000 or $10,000 insurance bill is something buyers factor into what they will pay.
Know your insurance story before you list. Gather your current policy, premium and carrier so buyers and their agents can see real numbers.
Show off fire-hardening work. Ember-resistant vents, defensible space, a newer roof and other mitigation can make a home easier to insure. That helps buyers get comfortable too.
Think about timing. As we said in May, the market doesn't stop, but today's buyer pool may be stronger than the one 6 to 12 months from now. If selling is already on your mind, it is worth talking through your timing now with an experienced real estate advisor..
Price with carrying costs in mind. A home that is expensive to insure competes for buyers whose monthly budget is already stretched.
The bottom line
What we flagged in May is now a reality: FAIR Plan rates have increased, and recent wildfires across Southern California underscore the growing challenges homeowners face when it comes to insurance. Beyond the financial implications, these events are a reminder of the very real impact wildfires have on families and communities.
Whether you're buying, selling, or simply evaluating your options, understanding how insurance availability and costs affect your real estate decisions is more important than ever. If you have questions about what these changes could mean for you, we're always happy to share our insights and help you navigate your next steps.
Sue & Gina De Legge, De Legge Team, Pacific Sotheby's International Realty. DRE 01304408 | 01746528